Written by Candice Klau, Managing Director, Be Covered Insurance Brokers
Candice specialises in construction insurance for builders, developers and construction businesses across Australia.
When you’re managing a commercial construction project, even a relatively small workmanship issue can become an expensive problem.
A waterproofing failure in a commercial fit-out, an incorrectly installed plumbing connection or defective work that damages another part of the building can lead to costly repairs, disputes and unexpected expenses.
For commercial builders, one of the most important questions is: Does Public Liability Insurance cover faulty workmanship?
The short answer is generally not the cost of fixing the faulty work itself. However, damage caused by faulty workmanship may be covered, depending on the policy wording and circumstances of the claim.
The distinction matters, particularly on commercial construction projects where multiple trades, substantial contract values and complex contractual obligations can increase a builder’s exposure.
Understanding how your insurance responds before something goes wrong can make a significant difference to the financial outcome.
What is considered faulty workmanship in commercial construction?
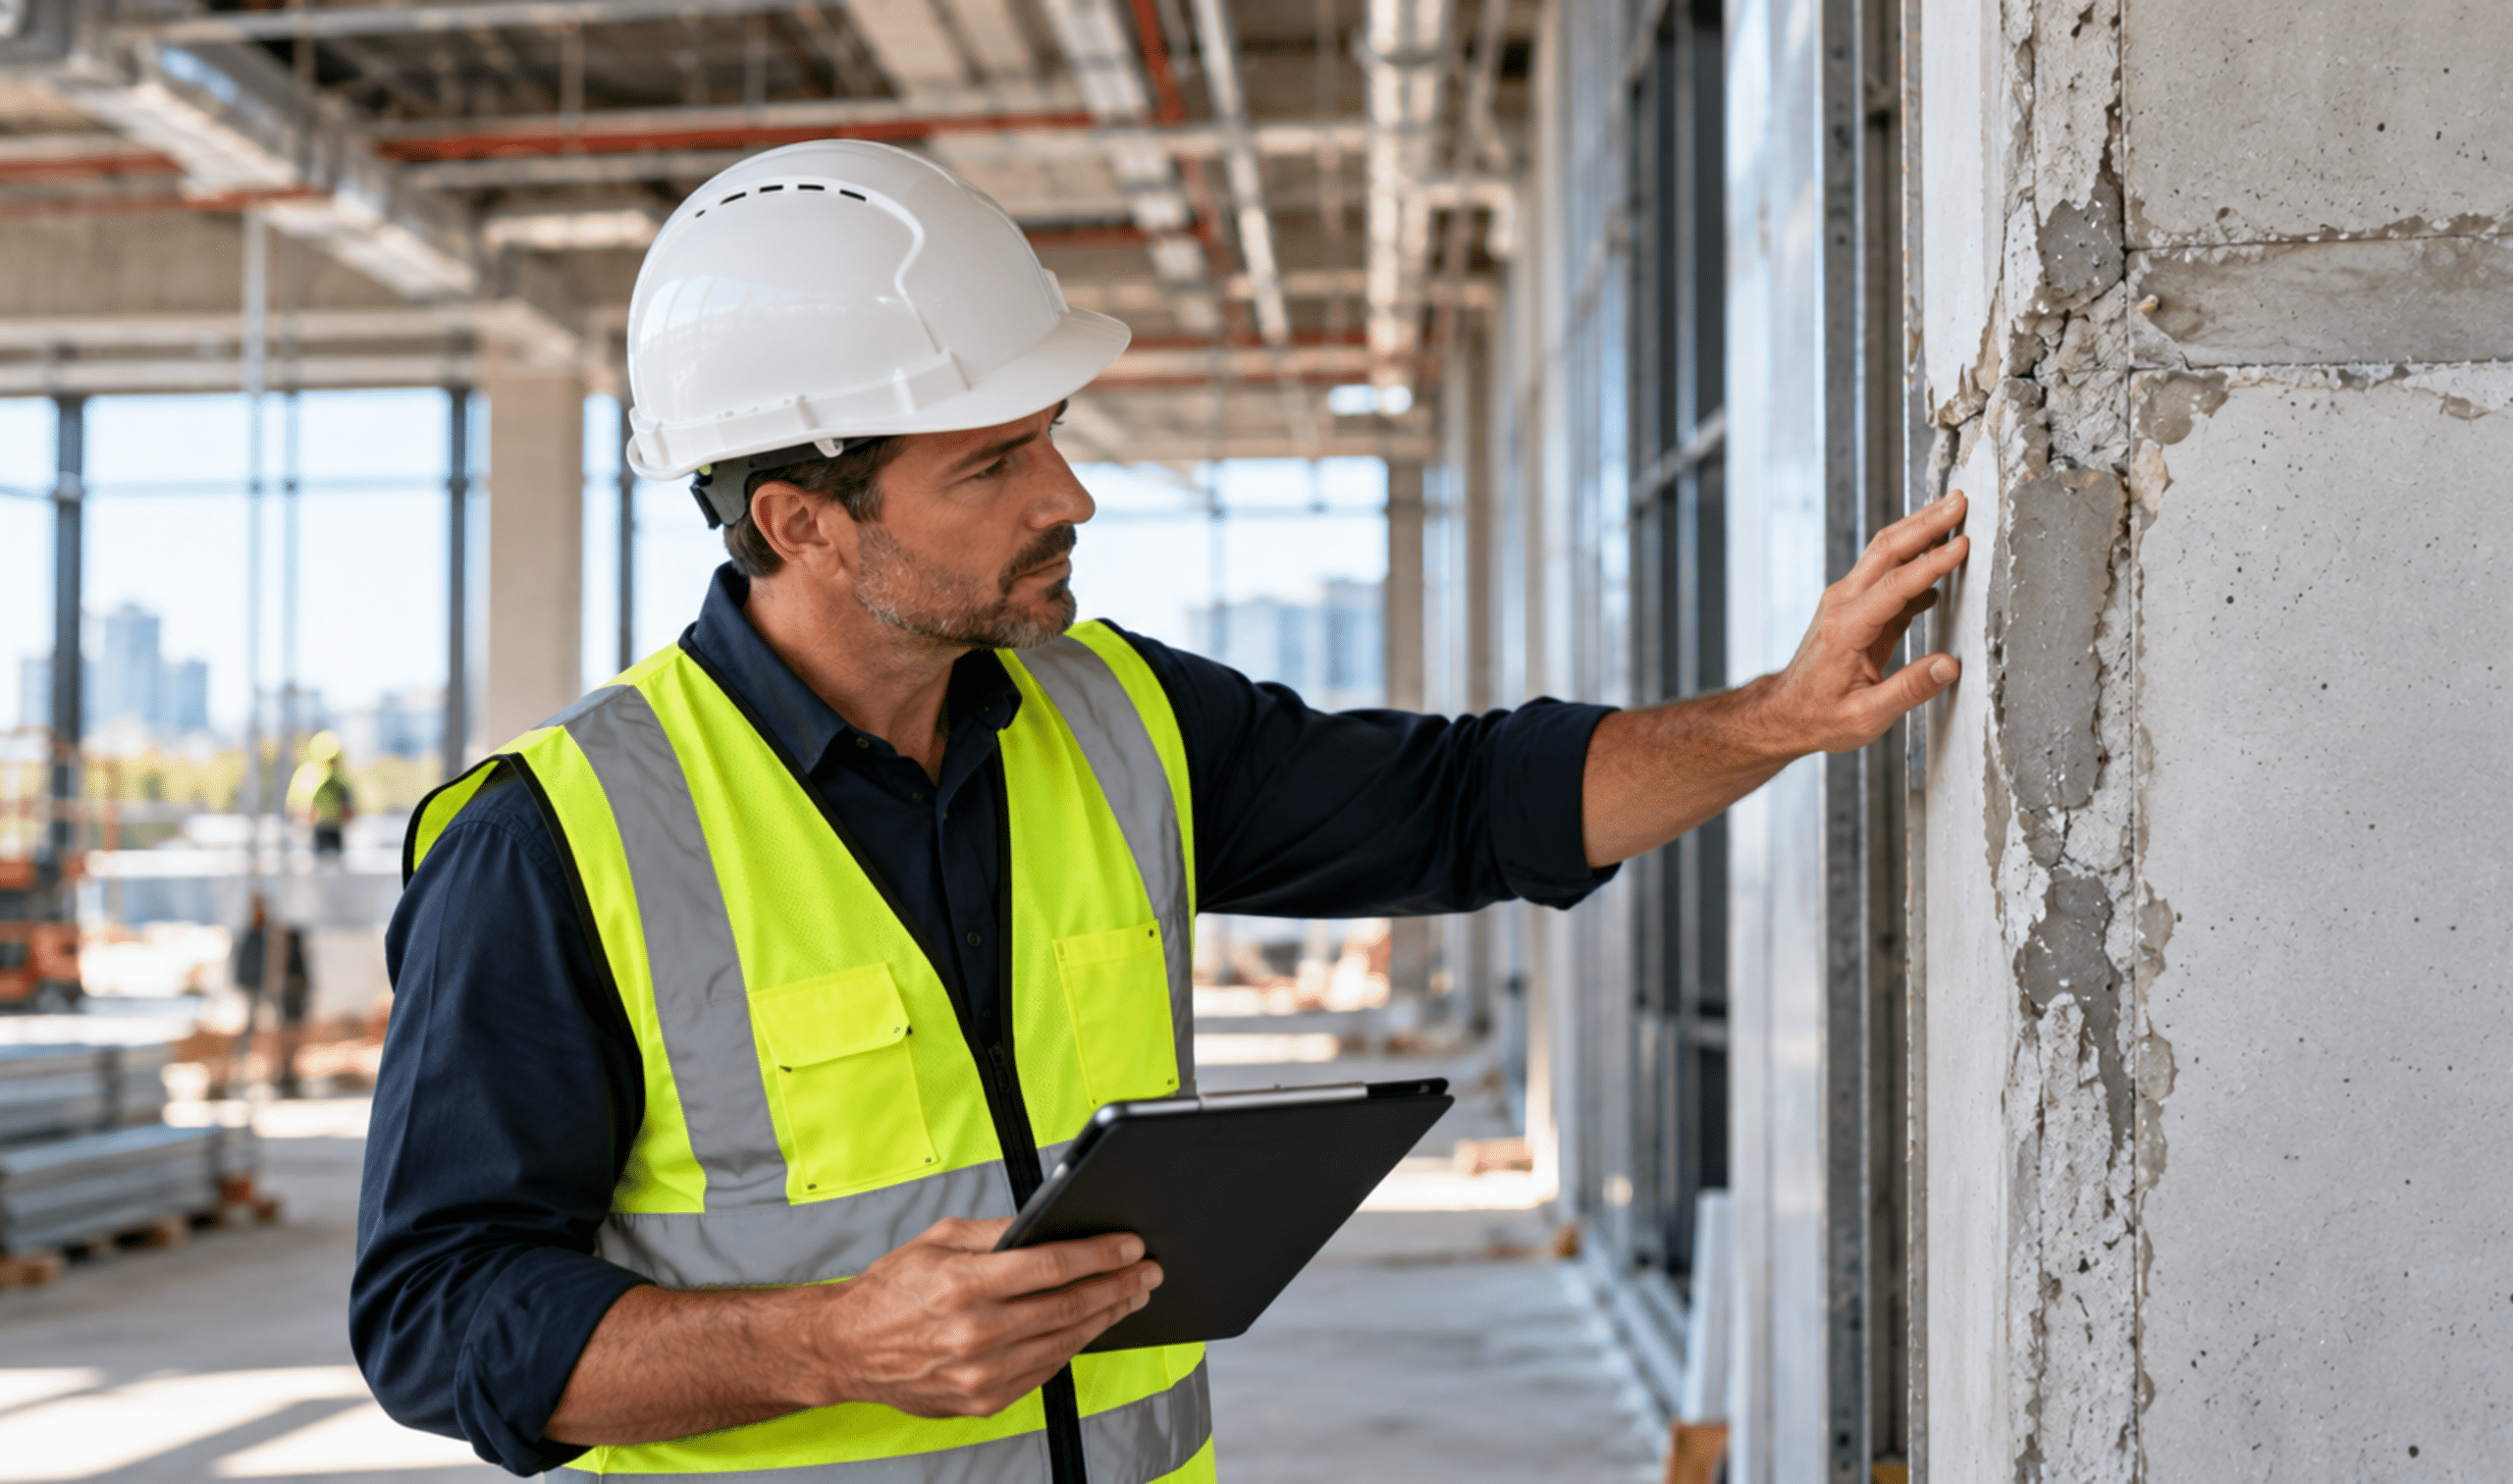
Faulty workmanship generally refers to construction work that has been carried out incorrectly, does not meet the required standard or fails to comply with relevant specifications.
On commercial projects, examples may include:
- Incorrect installation of waterproofing systems in commercial bathrooms.
- Poorly installed plumbing connections that result in leaks.
- Defective installation of roofing or cladding systems.
- Incorrectly fitted windows or façade components.
- Faulty installation of fixtures in a commercial fit-out.
- Construction work that does not meet the agreed specifications.
The issue becomes more complicated when the faulty work causes damage to another part of the building or to property belonging to someone else.
This is where understanding the difference between faulty workmanship and resulting damage becomes essential.
Faulty workmanship vs resulting damage: What’s the difference?
Public Liability Insurance is generally designed to respond to a business’s legal liability for certain third-party personal injury or property damage arising from its activities.
It is not intended to act as a warranty guaranteeing the quality of construction work.
Consider this hypothetical example.
A commercial builder is managing an office refurbishment. A plumbing connection is installed incorrectly, causing water to escape and damage completed flooring, internal walls and electrical fittings.
There are two separate issues:
1. The faulty workmanship
The incorrectly installed plumbing connection needs to be repaired or replaced.
The cost of correcting that defective connection would generally not be covered under a standard Public Liability policy.
2. The resulting damage
The escaping water has damaged other parts of the building.
Depending on the insurance policy, ownership of the damaged property, liability arrangements and relevant exclusions, some of this resulting damage may be covered.
The important distinction is that repairing the defective work and repairing damage caused by the defect are not necessarily treated the same way by insurers.
However, resulting damage is not automatically covered. Each claim needs to be assessed against the relevant insurance wording and the circumstances of the loss.
Why policy wording matters for commercial builders
One of the biggest mistakes a commercial builder can make is assuming that all Public Liability Insurance policies provide the same protection.
They don’t.
Some construction-specific insurance policies may provide broader protection for certain types of resulting damage than standard business liability policies.
An important consideration is how an insurer defines the part of the work that is defective.
For example, if a faulty component causes damage to a larger installation, one policy may exclude only the cost of correcting that component, while another may apply its defective-work exclusion to a broader portion of the installation.
The difference can significantly affect the amount potentially recoverable under a claim.
Other provisions can also influence the outcome, including:
- Definitions of insured property damage.
- Exclusions for defective work or products.
- Property in the builder’s care, custody or control.
- Damage to the works under construction.
- Contractual liability exclusions.
- Completed operations provisions.
- Policy excesses, limits and relevant extensions.
For builders managing high-value commercial projects, these details can have a considerable financial impact.
This is why reviewing the wording of your Public and Products Liability Insurance matters just as much as reviewing the insurance limit.
Three faulty workmanship scenarios commercial builders should understand
The following hypothetical scenarios demonstrate how insurance considerations can differ depending on the nature of the damage.
Scenario 1: Defective waterproofing in a commercial fit-out
A builder is completing the refurbishment of a commercial premises.
A subcontractor incorrectly installs waterproofing in a bathroom, resulting in water damage to adjacent flooring, wall linings and a neighbouring tenancy.
The builder may face costs associated with removing and replacing the defective waterproofing, repairing the surrounding damage and responding to a claim from the neighbouring tenant.
The cost of rectifying the defective waterproofing itself may be excluded.
However, resulting property damage to other areas could potentially fall within the scope of a relevant liability policy, subject to its terms.
What builders should consider: Does the policy distinguish between the defective work and damage caused to other property? How are subcontractor activities treated?
Scenario 2: Incorrect installation damages an existing commercial building
A contractor working on an occupied office building incorrectly installs a component, causing damage to existing property outside the construction works.
The builder may be held responsible for the damage under the construction contract or applicable law.
In this situation, the distinction between the existing building and the work being undertaken becomes important.
Depending on the circumstances, Public Liability Insurance or another relevant construction insurance arrangement may respond.
What builders should consider: Are existing structures, property in the builder’s care and the actual construction activities adequately addressed by the insurance program?
Scenario 3: Defective work discovered before any damage occurs
During an inspection of a commercial construction project, a builder discovers that an installed component does not meet the required specifications.
There has been no resulting property damage or personal injury.
The component must be removed and replaced before the project can proceed.
Because the issue involves correcting defective work rather than a covered third-party injury or property damage claim, standard Public Liability Insurance would generally not pay for the rectification.
What builders should consider: Insurance is not a substitute for quality control, contractual risk management or appropriate construction supervision.
These examples are illustrative only. Whether any particular claim is covered depends on the policy and the facts.
Does Contract Works Insurance cover faulty workmanship?
Commercial builders often arrange Contract Works Insurance alongside Public and Products Liability Insurance.
Although these covers may be packaged together, they serve different purposes.
Contract Works Insurance generally protects the insured construction works against specified physical loss or damage during the construction period.
Public and Products Liability Insurance generally addresses certain claims involving legal liability for third-party injury or property damage.
When faulty workmanship causes physical damage to the works themselves, Contract Works Insurance may be relevant.
However, Contract Works policies also contain defective design, materials and workmanship exclusions, and the treatment of resulting damage varies.
The fact that a builder has both policies does not mean every defect or associated repair cost will be insured.
For commercial projects, it is important to review how the different policies operate together and whether any gaps remain.
You can also read our Contract Works Insurance Checklist for Builders to understand other important policy considerations before starting a project.
What if the faulty workmanship was carried out by a subcontractor?
Commercial construction projects frequently involve several subcontractors working under the direction of a head contractor.
A common assumption is that if a subcontractor causes the problem, responsibility automatically sits with that subcontractor.
Unfortunately, it is not always that simple.
Depending on the construction contract and circumstances, the head contractor may still be responsible to the principal for rectifying defective work or responding to damage caused by subcontractor activities.
Even where a subcontractor holds Public Liability Insurance, that does not automatically mean the head contractor is protected against every related claim.
Commercial builders should consider:
- Whether subcontractor activities have been correctly disclosed to their insurer.
- Whether the subcontractor holds suitable insurance for the work being undertaken.
- How contractual responsibilities are allocated.
- Whether the head contractor’s policy responds to liability arising from subcontracted work.
- Whether the principal’s insurance requirements have been satisfied.
For projects involving multiple trades and contractors, insurance arrangements should reflect how the work is actually delivered.
Five insurance questions commercial builders should ask before starting a project
Faulty workmanship claims can be complicated, but there are practical steps builders can take to understand their exposure.
1. How does my policy define defective workmanship?
Ask your broker to explain which parts of the work could be excluded if a defect causes damage.
2. Is resulting damage covered?
Understand whether the policy may respond to damage caused by defective work and what conditions or exclusions apply.
3. Am I covered for work carried out by subcontractors?
Ensure your insurer understands your subcontracting arrangements, including the type of work being undertaken.
4. Does my insurance reflect my contractual obligations?
Commercial construction contracts may include indemnities, insurance requirements and other responsibilities that go beyond standard policy protection.
Your insurance should be reviewed against the relevant contract before you accept those obligations.
5. Have my projects or activities changed?
Larger projects, new construction methods, different types of commercial work or changes to project responsibilities may create exposures that were not considered when your policy was first arranged.
If your business is taking on larger or more complex projects, read our guide: Moving Into Bigger Commercial Projects? 7 Insurance Issues Builders Should Review Before Tendering.
Why specialist construction insurance advice matters
For commercial builders, choosing insurance is not simply about securing a Certificate of Currency or meeting a minimum Public Liability limit.
The wording of the policy, the types of projects being undertaken and the contractual responsibilities assumed by the builder can all influence how insurance responds when something goes wrong.
Two policies with the same liability limit may provide different outcomes for the same construction-related incident.
At Be Covered Insurance Brokers, we specialise in helping commercial builders across Australia understand their construction insurance arrangements.
We take the time to review the nature of your projects, construction contracts, subcontractor arrangements and policy wording to help identify potential gaps before they become costly problems.
Our role is to help you understand what your insurance is designed to cover, what it may exclude and where your business may remain exposed.
Frequently Asked Questions
Does Public Liability Insurance cover faulty workmanship in Australia?
Generally, Public Liability Insurance does not cover the cost of correcting faulty workmanship itself. However, damage caused by faulty work may be covered in certain circumstances, depending on the policy wording, the damaged property and the nature of the claim.
Does Public Liability Insurance cover damage caused by defective construction work?
It may. Some policies can respond to legal liability for resulting third-party property damage caused by faulty workmanship. However, exclusions for defective work, property being worked on and other policy conditions can affect the outcome.
Will insurance pay to redo defective building work?
Not usually under a standard Public Liability policy where the claim is solely for rectifying defective workmanship. Different insurance arrangements may respond to particular insured losses, but builders should not assume rectification costs are covered.
Does Contract Works Insurance cover damage caused by faulty workmanship?
Contract Works Insurance may cover certain physical damage resulting from defective workmanship, depending on the policy. The defective work or component itself may be excluded, and different insurers can apply different defects exclusions.
Is a commercial builder responsible for faulty work completed by a subcontractor?
A commercial builder may have contractual or legal responsibilities for work performed by subcontractors. The extent of those responsibilities depends on the contract and circumstances. Insurance should be reviewed to understand how subcontractor-related liability is addressed.
What insurance should commercial builders review for faulty workmanship risks?
Commercial builders should review their Public and Products Liability and Contract Works Insurance. Where work involves design or professional services, Professional Indemnity Insurance may also be relevant. Each policy responds to different risks and should be considered alongside the builder’s contractual obligations.
Is your commercial construction insurance covering the risks you think it is?
Faulty workmanship can create financial exposure well beyond the cost of correcting the original defect.
For commercial builders, understanding how Public Liability Insurance treats defective work and resulting damage is essential.
Don’t wait until a claim to discover how your policy responds.
Be Covered Insurance Brokers helps commercial builders across Australia review their construction insurance, understand policy exclusions and identify potential gaps in cover.
Contact Be Covered Insurance Brokers to discuss your commercial construction insurance arrangements.
General information only. This article does not constitute personal insurance or legal advice. Coverage depends on the terms, conditions, limits and exclusions of the relevant policy and the circumstances of each claim.