Written by Candice Klau, Managing Director, Be Covered Insurance Brokers
Candice has more than 20 years of insurance broking experience and specialises in construction insurance for commercial builders across Australia.
A commercial construction contract can create financial obligations well beyond the cost of delivering the project. Before a head contractor signs, it is worth asking a question that is often overlooked: if a dispute or loss arises, will the insurance respond to the liabilities accepted in the contract?
Not every contractual promise is automatically insured. Construction contracts may transfer risks through indemnities, insurance requirements and obligations relating to the principal, subcontractors and existing property. The policy wording must be considered alongside those obligations.
What is contractual liability in commercial construction?
Contractual liability arises when a business accepts responsibilities under an agreement. For commercial builders, these may include promises to indemnify a principal for certain losses, meet specified insurance limits or take responsibility for the activities of subcontractors.
An indemnity clause can require one party to compensate another for defined losses. Its scope depends on its wording and the applicable law. Agreeing to an indemnity does not, by itself, extend an insurance policy.
For example, a principal may ask a builder to accept responsibility for damage to an existing warehouse during a major extension. Whether an insurance policy responds may depend on the legal basis of the claim, the nature of the damaged property and exclusions for assumed contractual liability or property being worked on.
Why can there be a gap between a construction contract and insurance?
Public and Products Liability Insurance generally addresses certain claims involving legal liability for third-party injury or property damage. It is not a guarantee that every contractual obligation will be funded.
Potential differences can arise where a contract requires a builder to accept liability broader than would otherwise apply, take responsibility for another party’s acts, or meet certain costs even where there is no insured property damage or injury.
Builders managing design-and-construct projects must also consider professional responsibilities. Public Liability and Professional Indemnity Insurance address different exposures and may have different conditions, limits and exclusions.
A Certificate of Currency demonstrates selected policy information; it does not establish that all indemnities, endorsements or obligations in a construction contract are insured.
A practical example: storm damage to an existing commercial building
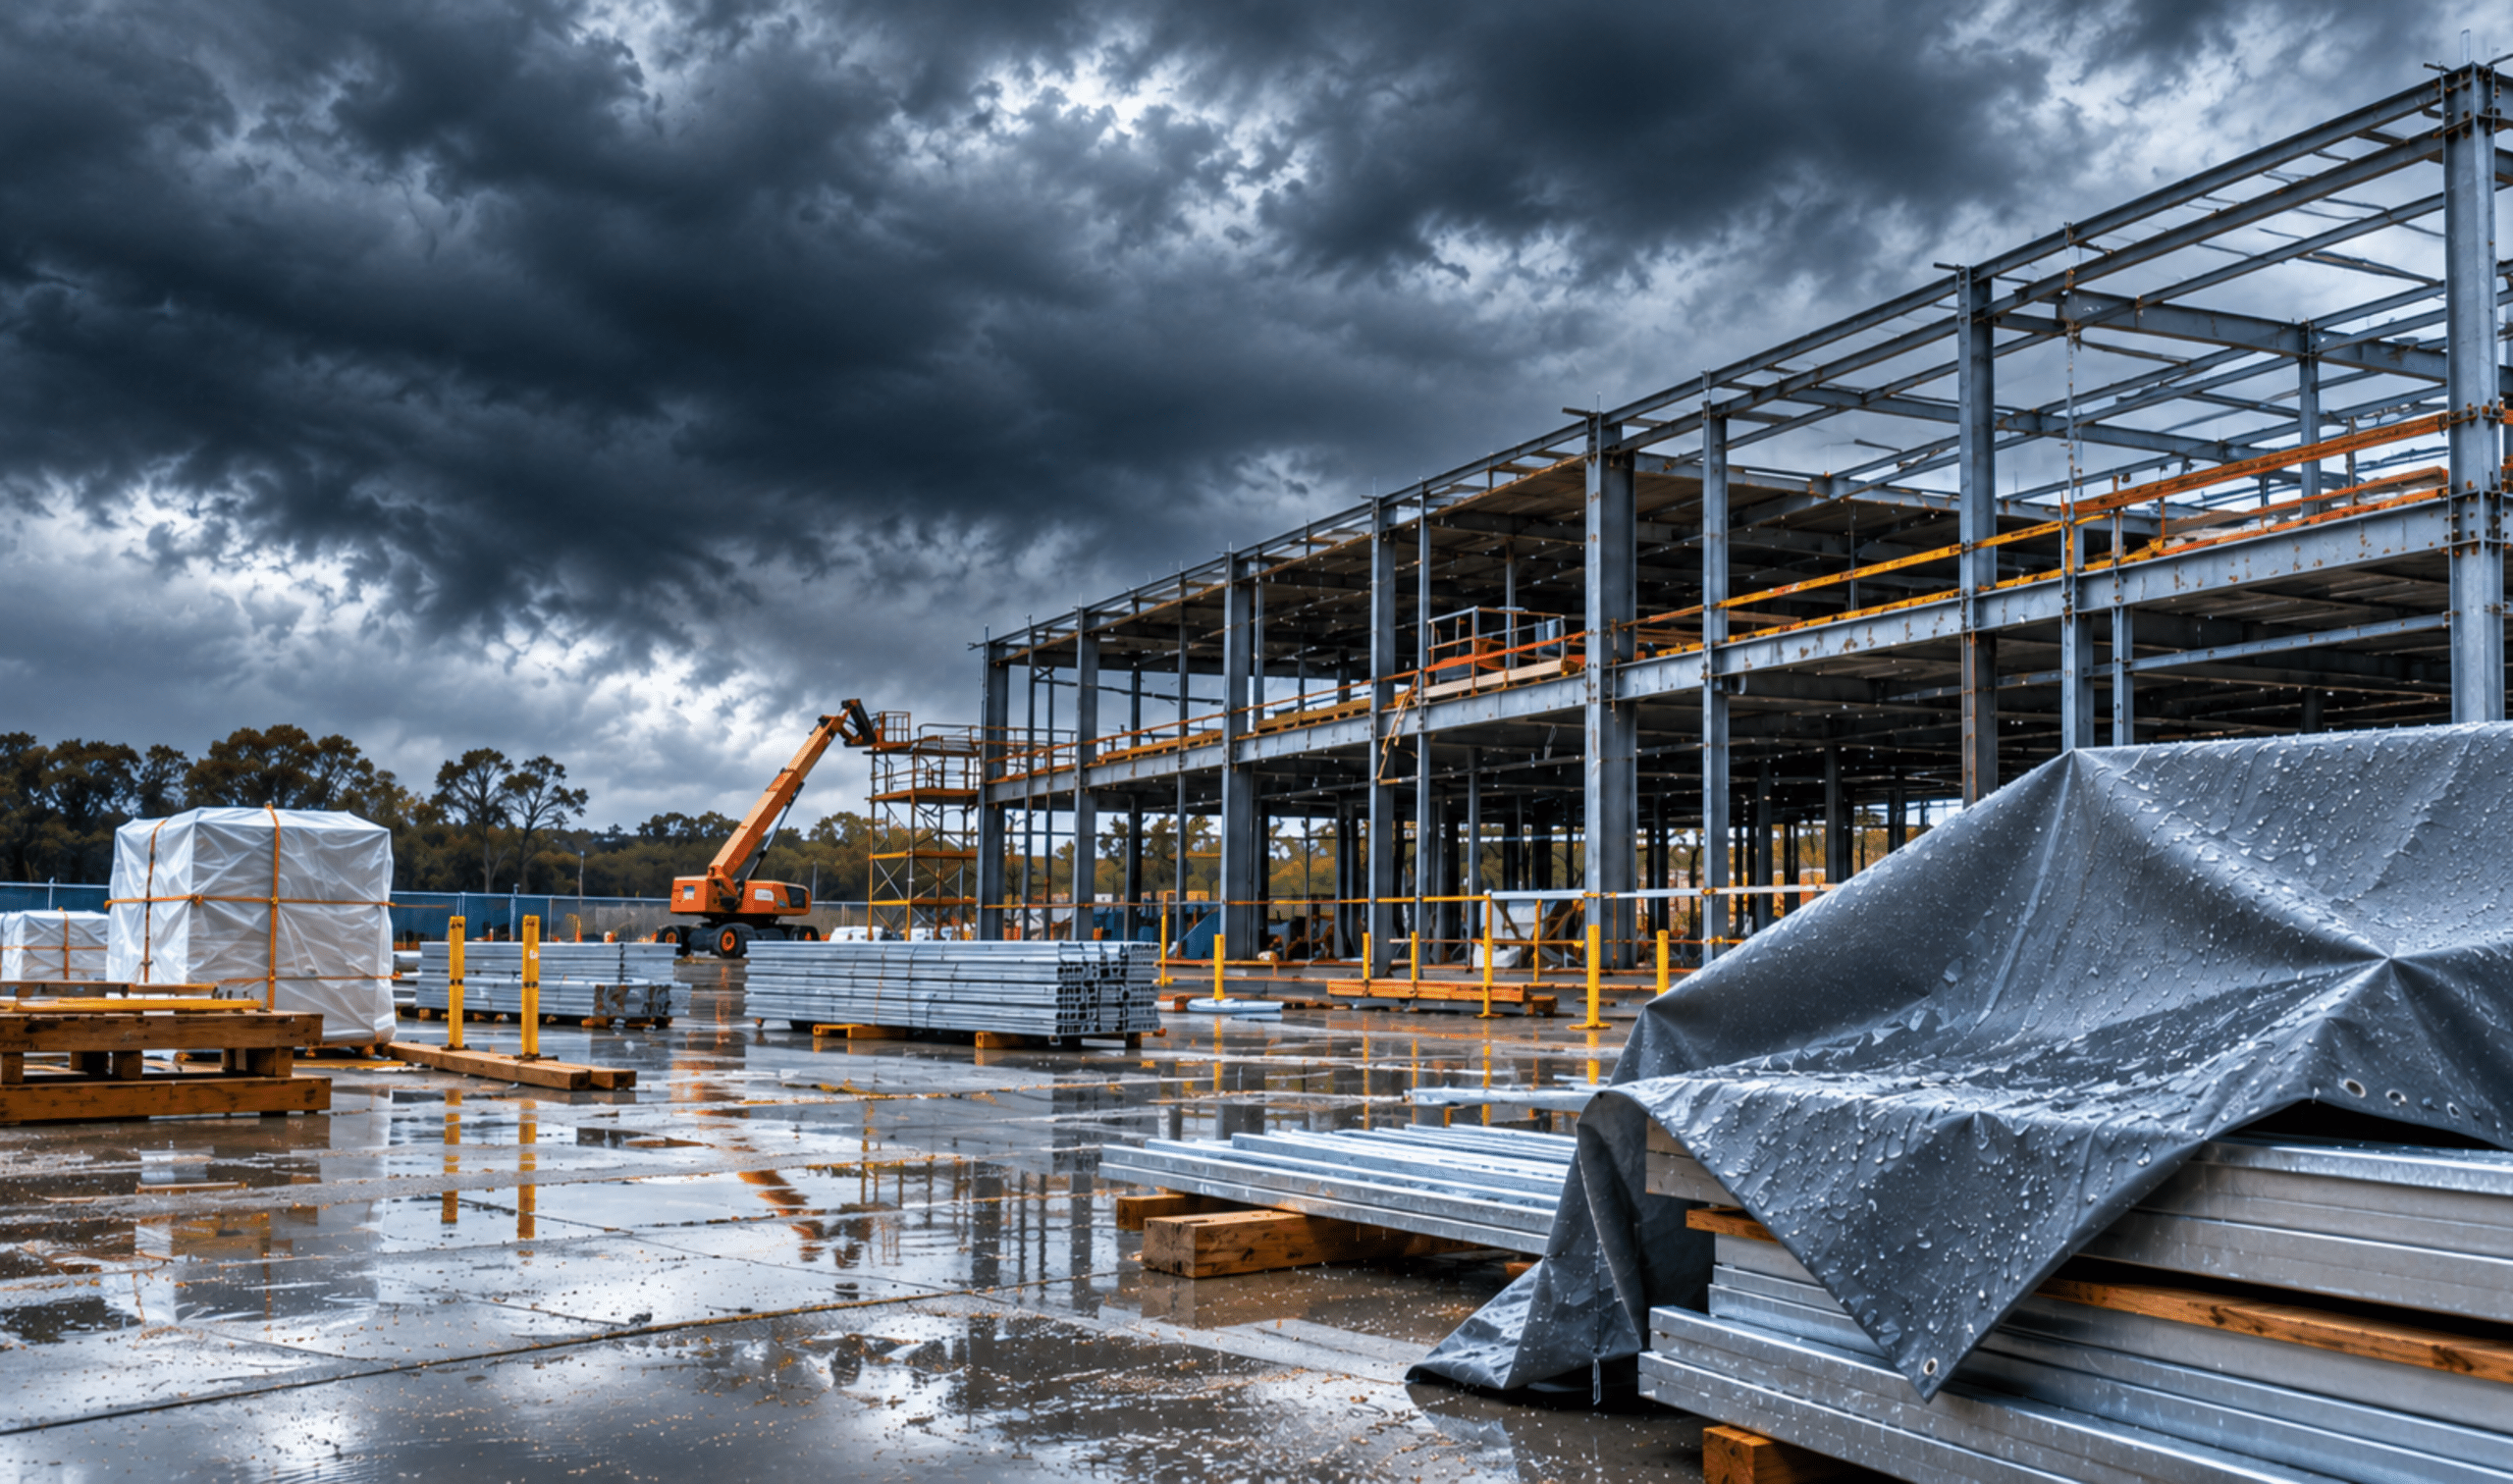
Consider a head contractor undertaking an extension to an existing commercial building. During construction, a severe storm causes significant damage to an unrelated section of the existing building, well away from where the builder is working.
Under the contract, the builder has accepted responsibility for damage to the existing structure during construction, regardless of fault. However, Contract Works Insurance may not cover the existing building unless specifically arranged, and Public Liability Insurance may not respond where the builder has no legal liability outside the contract.
The result? The builder could be contractually responsible for hundreds of thousands of dollars in storm damage they didn’t cause, without insurance that responds to the loss.
Four checks before signing a commercial construction contract
- Review indemnity clauses. Identify which losses you are accepting responsibility for, including losses caused partly by others or unrelated to your own negligence.
- Compare contract requirements with policy wording. Check insured activities, existing property, contractual liability exclusions, limits, excesses and required endorsements.
- Check design and subcontractor obligations. Understand how design responsibilities and subcontracted work affect your insurance arrangements.
- Resolve unclear requirements before signing. Ask your specialist broker to review insurance clauses, and seek legal advice on the contract’s risk allocation where needed.
For more information about the different parties involved in a commercial project, read our guide to who is responsible for insurance on a commercial construction site.
Why specialist construction insurance advice matters
For established commercial builders, a new project may introduce different principals, larger indemnities, design duties or existing-building exposures. Insurance that suited the last project may not align with the next contract.
At Be Covered Insurance Brokers, we help commercial builders review construction insurance requirements and identify potential gaps between their policies and the risks they are taking on. Before signing, make sure you know which obligations are insured and which may remain your responsibility.
Discuss your commercial construction insurance arrangements with Be Covered Insurance Brokers.
General information only. Insurance cover depends on policy terms and claim circumstances. Contract interpretation and enforceability require legal advice.